Best practices for avoiding common pitfalls with pass-through costs
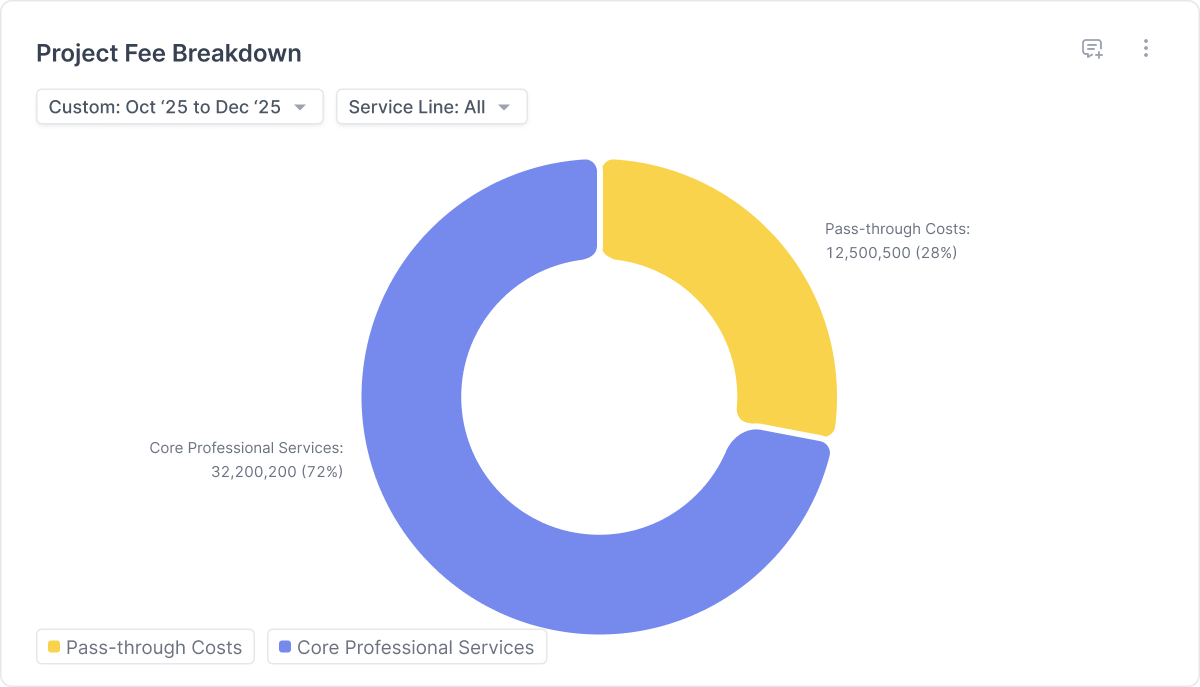
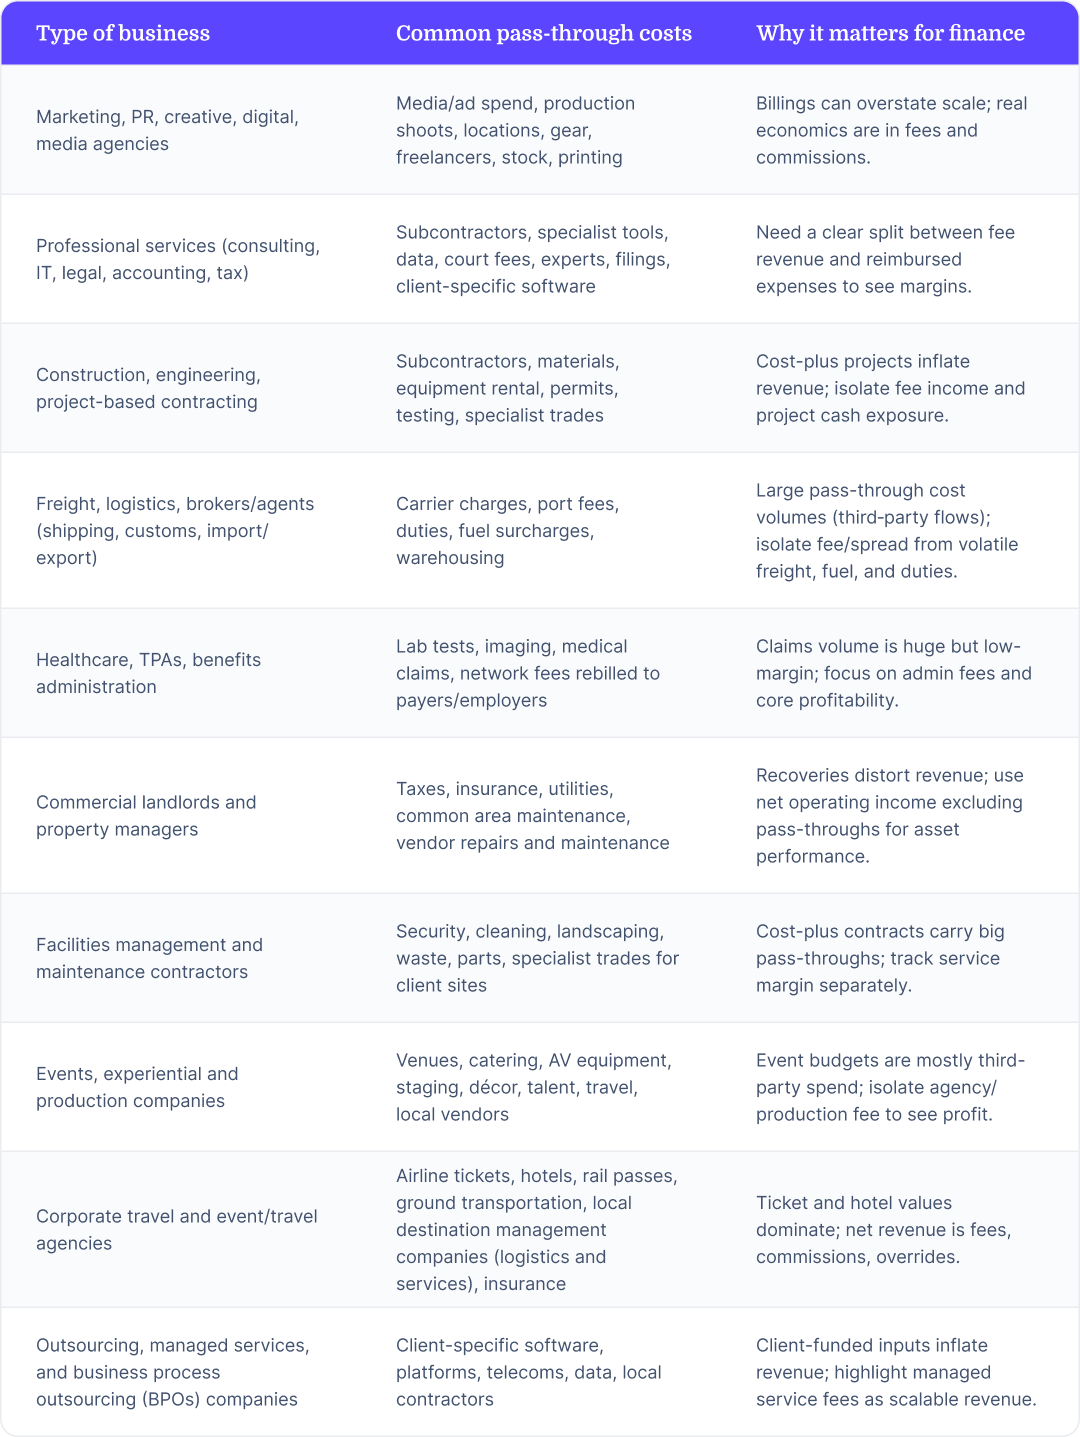
Pass-throughs can create three big problems for finance teams: they distort your metrics and KPIs, they mislead leadership about real performance, and they create incentives for teams to chase high-volume, low-margin work.
The five practices below will help you eliminate those distortions at every level—from your GL structure to your forecasts to executive dashboards.
1. Collaborate with accounting teams
Finance and accounting teams have different goals when it comes to pass-through costs. Accounting focuses on correctness and compliance, but your priority is insights that help you make better decisions. Working with your accounting team is essential to accurately track pass-through costs.
Why it matters
If your accounting team treats pass-through costs differently from the method described in the contract, you'll spend hours every month trying to identify and strip out pass-throughs manually in spreadsheets.
How to avoid the pitfalls
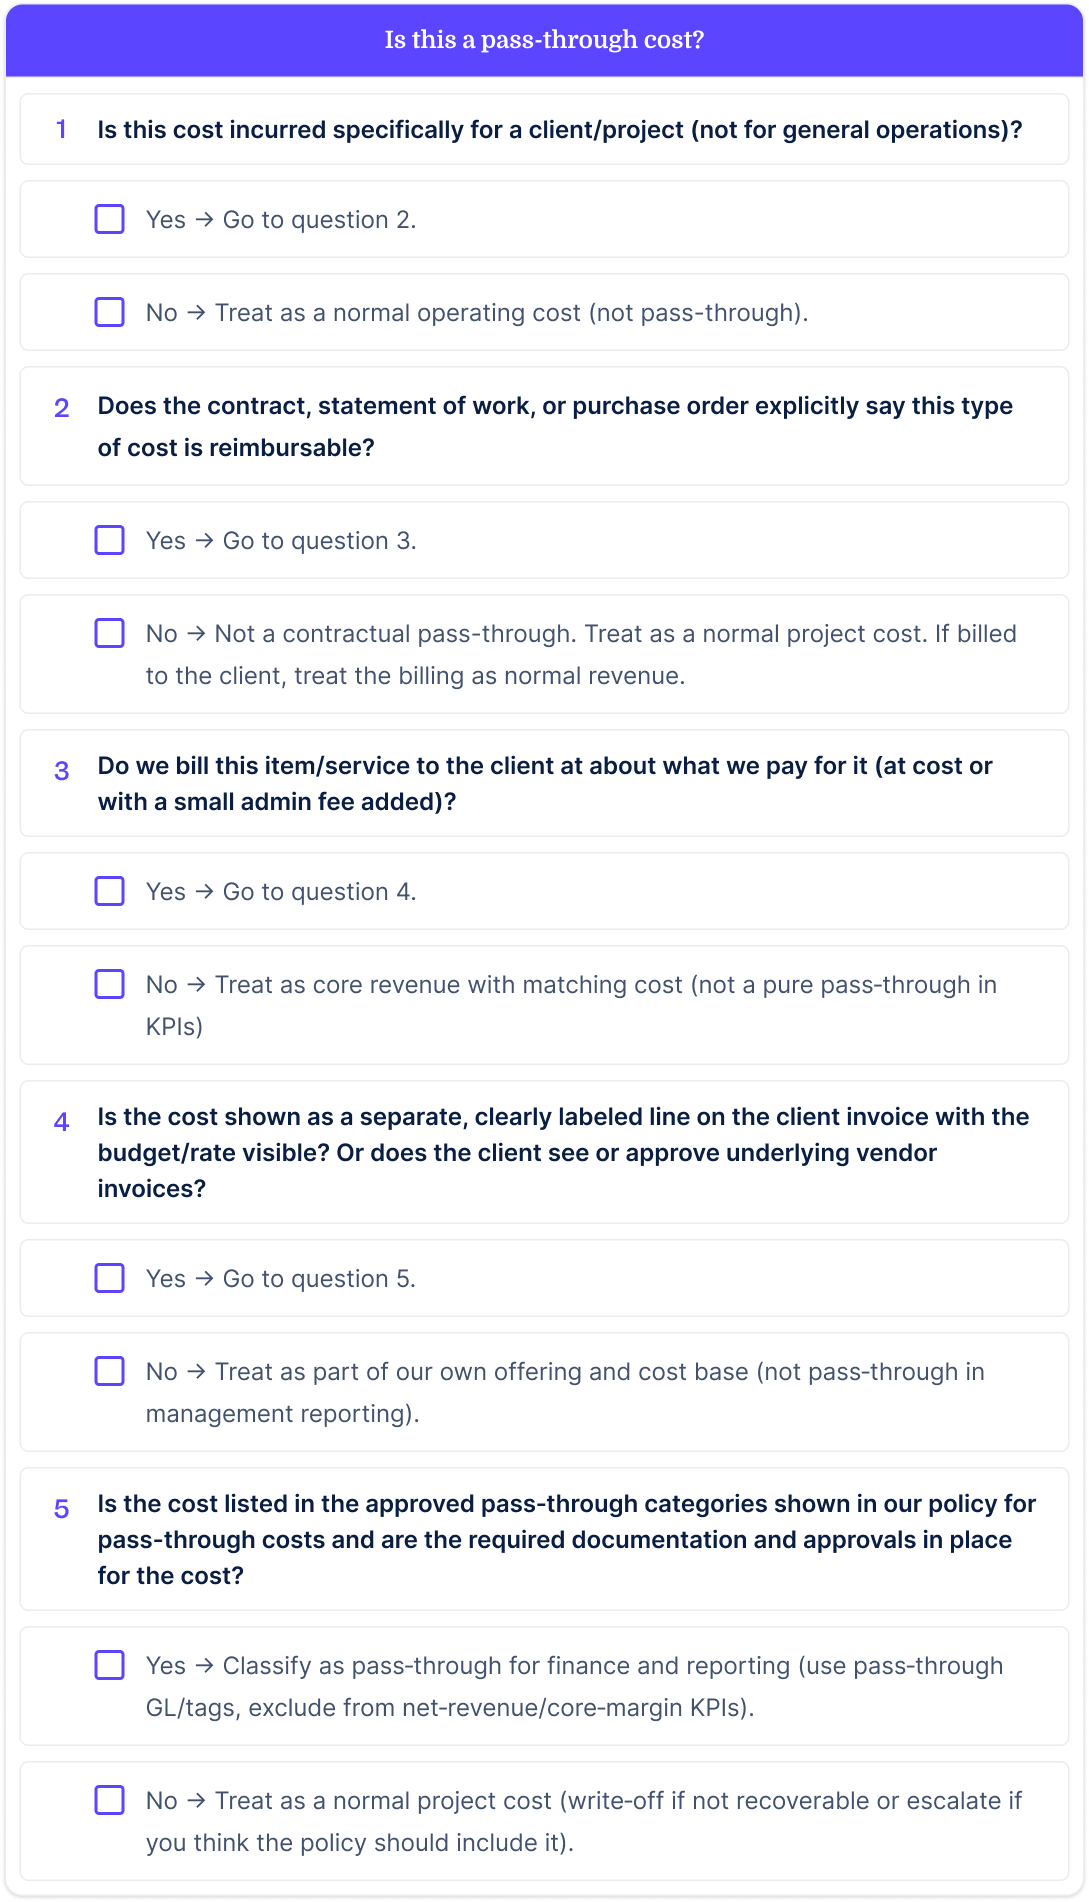
The best way to achieve your goals as the finance team is to isolate pass-through costs in dedicated GL accounts or account groups rather than mixing them with core revenue or operating costs.
To make sure everyone wins, work with your accounting team to make pass-through costs clearly identifiable in the ledger. Ask them to provide:
- Clear reporting mappings where pass-through items appear as separate lines
- Dedicated accounts or account ranges for pass-through costs and reimbursed revenue
Once you do this, you’ll have accurate margin data (that excludes pass-throughs) and unit economics that reflect true value-add. You’ll be able to benchmark across teams and peers using net revenue, and build forecasts faster with pass-throughs modeled separately from core pricing.
When reporting, just make sure you always show reported (gross) and net revenue side-by-side with clear labels to help your leadership understand both the volume story and the economic story.
2. Align incentives to net revenue and margin
Bonuses, commissions, and other performance-based incentives should be tied to net revenue and margin, not gross billings that include pass-throughs. If you need to use gross billings to track scale or market share, pair them with explicit margin targets so your team isn't rewarded for pushing volume alone.
Why it matters
Incentives tied to gross billings that include pass-throughs can push your sales and delivery teams toward high-volume, low-margin activity.
How to avoid the pitfalls
Explicitly define "qualifying revenue" or "commissionable revenue" as the net of pass-throughs in your compensation plan documents.
Run test scenarios with finance and sales leadership using recent deals to make sure the new structure rewards the behavior you actually want—margin and profitability, not just volume.
If you're keeping gross billings metrics for market positioning or scale tracking, create a paired scorecard that shows both gross billings and net revenue/margin targets together, with clear thresholds so no one can hit their number on volume without delivering profit.
3. Refine KPIs to eliminate pass-through distortion
It’s important to exclude pass-through costs from the formulas your systems use to compute core KPIs like contribution margin, revenue per FTE, customer LTV, and CAC.
You can still track pass-through volumes separately for operational context—just don't let them feed into the metrics that measure real performance and profitability.
Why it matters
Your dashboards will tell a story that doesn't match your P&L. And your leadership will end up making strategic decisions, resource allocations, and growth commitments based on metrics that don't reflect true economic performance.
How to avoid the pitfalls
Start by auditing which KPIs and dashboards currently use gross revenue or total billings as inputs. Recalculate them using net revenue (revenue minus pass-throughs) as your base. Update your planning and BI tools to automatically flag or separate pass-through flows so they don't contaminate core metrics by default.
Build dashboard views that show both gross and net versions of key metrics side-by-side during the transition so stakeholders can see the difference and understand why you're making the change.
4. Model pass-through costs separately and run scenarios
It’s best to model your pass-through costs based on their own drivers—things like client budgets, project scope, usage volumes, or external rates—as opposed to a straight percentage of core revenue. You should also forecast core revenue and pass-throughs separately, then add them up to see the full picture.
Once you've got separate models, run scenarios that isolate what happens when pass-throughs move independently:
- What if pass-through volume spikes but core revenue stays flat?
- What if core revenue grows but pass-throughs stay stable?
If there's a real connection between pass-through volumes and your core business (common in project-based work or budget-linked models), call that out explicitly rather than pretending they're totally independent.
Why it matters
Pass-through costs are usually volatile and driven by things you don't control. If you lump them in with core revenue, your forecasts will swing wildly for reasons that have nothing to do with your core business.
How to avoid the pitfalls
Start by pulling out pass-through volumes from your current financial data and getting clear on whether you're billing them at cost or adding a markup.
Build separate forecast drivers for pass-throughs (like "client media budget assumptions" or "expected freight volume") and for core revenue (like "service fees," "active clients," "pricing"). Add them together for your total reported revenue, but always show them side-by-side so leadership can see both the volume story and the real economics.
Run at least two scenarios in each planning cycle to show how different pass-through assumptions change your reported numbers without changing your actual profitability. Make sure to flag any real correlation between pass-through activity and core drivers so stakeholders understand when the two actually move together.